- Content
Transferring funds from the Middle East to the EU via Cyprus in 2026 requires a clear legal and banking framework. Cyprus is a member of the European Union, applies European anti-money laundering regulations, and monitors transactions conducted through banks, payment institutions, and professional intermediaries.
AML stands for anti-money laundering, and KYC stands for know your customer. In practice, this means that the bank is required to verify the payer’s identity, the source of funds, the purpose of the payment, and the transaction’s connection to Cyprus. If funds pass through a Cypriot account without an economic justification, the bank will request additional documentation or reject the transfer.
Legal Transfer Methods
Legal capital transfers typically take the form of SWIFT bank transfers, transfers between personal accounts, corporate payments under a contract, dividend distributions, loan repayments, real estate payments, or investment contributions. Each method requires supporting documentation. The bank needs to see why the money is being transferred, who is sending it, and on what basis the recipient is receiving the funds.
Cyprus is suitable for the transit of capital into the EU if the client has a genuine connection to the jurisdiction. This could be tax residency, a company, a real estate purchase, obtaining residency, a family relocation, or an investment structure. Without such a connection, the transaction appears to be a formal transit, which triggers stricter compliance controls.
In business practice, the following channels are most commonly used:
- a personal transfer to a Cypriot account for living expenses, real estate purchases, or family expenses;
- a corporate transfer under a service, supply, loan, or profit distribution agreement;
- a transfer to a real estate seller after inspecting the property and agreeing on the purpose of the payment;
- a transfer through a licensed payment institution, provided the route has been pre-approved by the bank.
Separate EU rules apply to transactions involving crypto-assets. Regulation 2023/1113 requires that transfers be accompanied by information about the payer and the payee. This applies to payment service providers and crypto-asset service providers if the transaction falls within the scope of regulation.
Key Risks and Limitations
The main risk is not related to the transfer itself, but to insufficient supporting documentation. The bank will hold up the transaction if the customer fails to disclose the source of the funds, does not identify the ultimate beneficiary, uses multiple companies without a business justification, or transfers funds from a jurisdiction with a high sanctions risk.
A separate issue is discrepancies in documentation. For example, funds come from one company, the contract is signed by another, and the beneficial owner is not disclosed. To the bank, this arrangement appears to be an attempt to sever the link between the source of the capital and the recipient.
There are also currency and tax risks. Transfers from Middle Eastern countries are often made in U.S. dollars through correspondent banks. Each participant in the chain conducts its own due diligence. If the ultimate goal is to purchase an asset in the EU, commissions, the conversion rate, tax implications, and payment processing times are calculated in advance.
Practical Recommendations
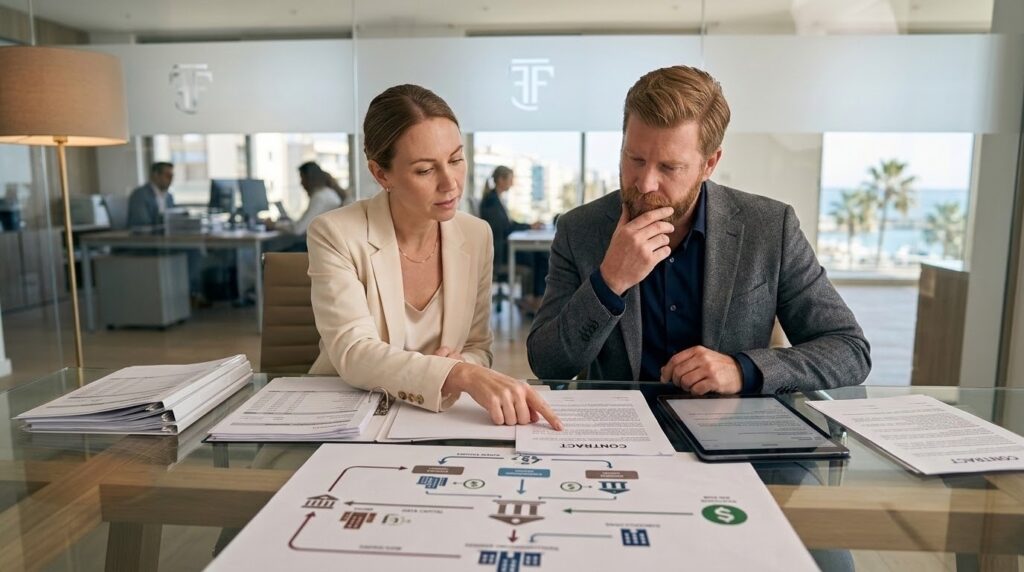
Before making a transfer, it’s a good idea to compile a single file for the transaction. This file should include the contract, bank statements, tax documents, proof of the asset sale, the dividend resolution, the ownership structure, and a brief explanation of the payment route. Such a document helps the bank understand the economic rationale behind the transaction more quickly.
For large amounts, it is best to coordinate the transfer with the bank before sending the funds. You should also choose the currency based on the purpose of the transaction: the euro is convenient for real estate and expenses within the EU, while the U.S. dollar makes sense if the source of capital is in the Gulf states and the funds pass through the dollar-based infrastructure.
Legal support is required prior to the payment. A consultant reviews the contract, the tax implications, the source of funds, and the bank’s requirements. For Almanova Law clients, this preparation is particularly important when purchasing real estate, applying for residency, repatriating dividends, and transferring family capital to Cyprus.
Elina Almanova
Advocate